
Office Property Market Indicators
Knight Frank has observed a rising trend in Asset Enhancement (AE) and improvements aimed at revitalizing aging properties to maintain their competitiveness in the market. These efforts have evolved from purely basic physical refurbishments to now include the integration of advanced technologies and sustainable practices, thereby enhancing both the functionality and appeal of the properties.
23 April 2024
Key Figures
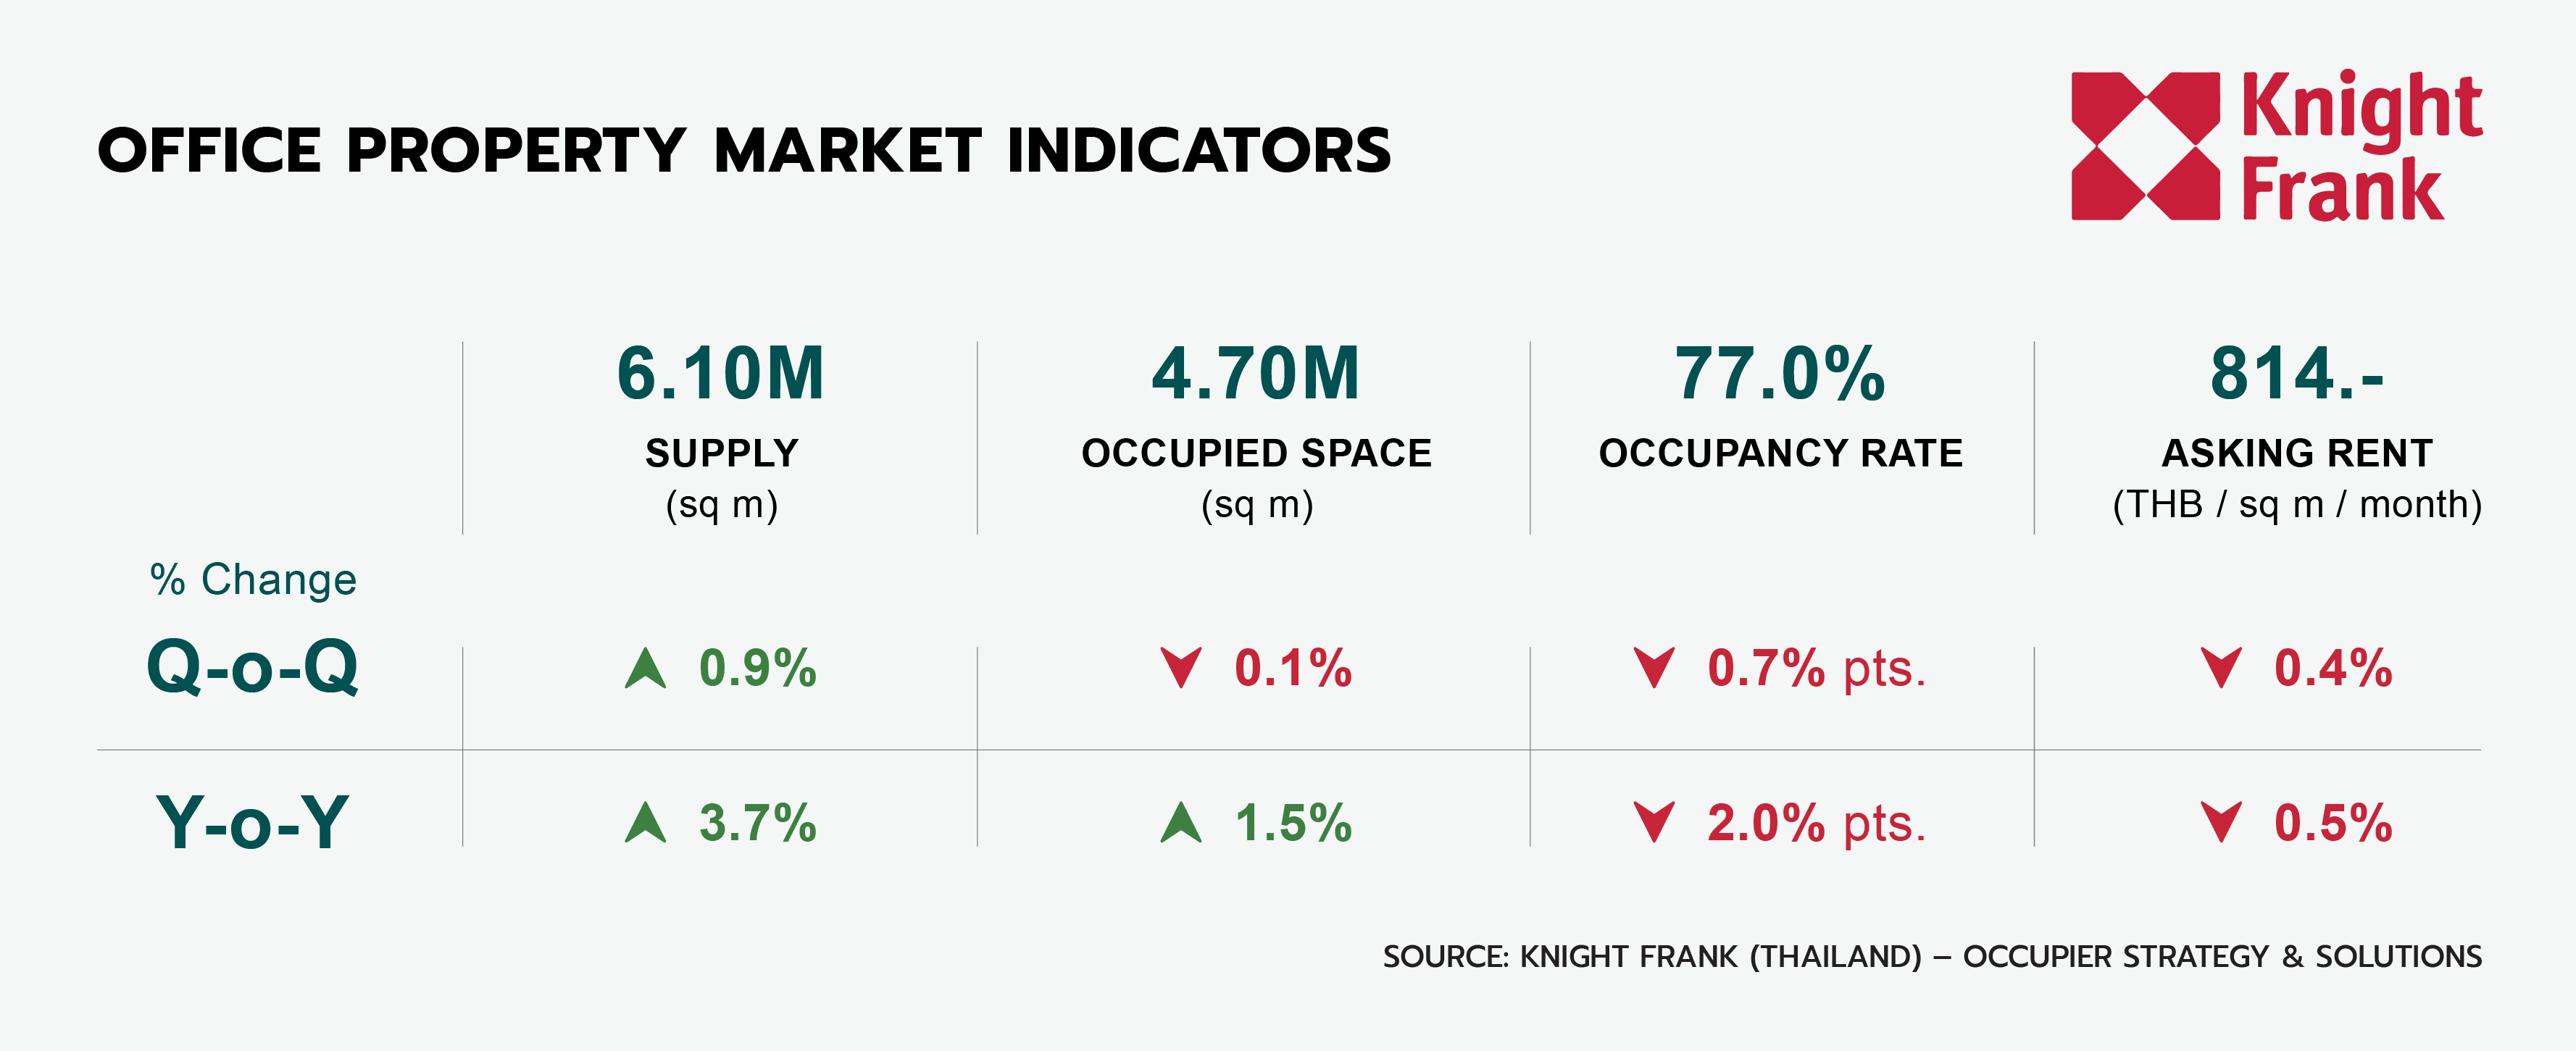
- The total supply of office space in Bangkok increased by 52,700 sq m, from the completion of Punn Tower and JLK Tower, bringing the total to 6.10 million sq m.
- 1.47 million sq m is in the projected pipeline from 2022 to 2028.
- Net absorption declined by -5,500 sq m in Q1.
- The overall occupancy rate declined by 0.6% pts QoQ to 77.0%.
Economic Overview
The Office of the National Economic and Social Development Council (NESDC) revised the Thailand outlook for 2024 to 2.7%, down from the previous estimate of 3.2%. Both private consumption and private investment are expected to expand by more than 3%. However, public consumption is anticipated to slow to 1.5%, with public investment contracting by 1.8%, after a delay of over six months in state budget planning for fiscal 2024. In the external sector, exports of goods and services are forecast to grow by 5%, outpacing the expansion of imports, which will increase by 3%. Consequently, the NESDC expects that net exports will be another key economic driver this year, alongside private consumption and private investment, amid low inflationary pressures, low unemployment, and the anticipated cessation of the policy interest rate rise.
Economically, February 2024 saw a decrease in headline inflation across all major categories, remaining at -0.8% YoY. This decline was primarily influenced by the high base effect from the previous year and increased supplies in fresh food and energy markets. Additionally, there was a slight downturn in the labor market, with rising unemployment rates observed in both production and service sectors. The Thai Baht weakened against the US dollar amid expectations of a delayed interest rate cut by the Thai central bank. Throughout 2024, the Thai economy is likely to confront multiple risk factors, including rising household debt, potential drought conditions, and ongoing global geopolitical tensions.
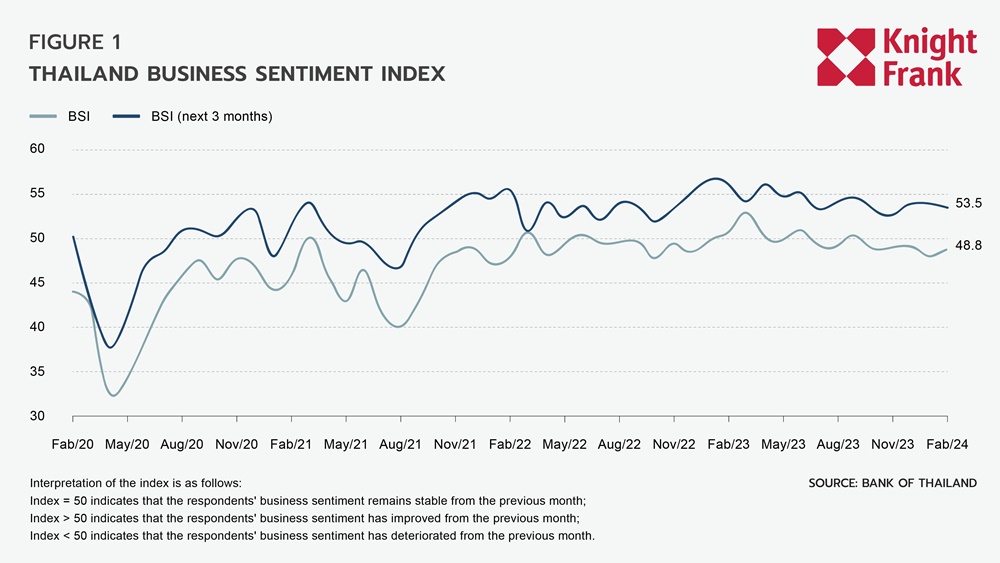
The Business Sentiment Index (BSI) for February 2024 slightly contracted to 48.8 from 49.1 in December of the previous year. The data indicated a decrease in confidence regarding costs and total order books, except for employment. The projected BSI for the next three months also decreased by 0.5 percentage points to 53.5, affecting almost all components, except for investment confidence.
Supply
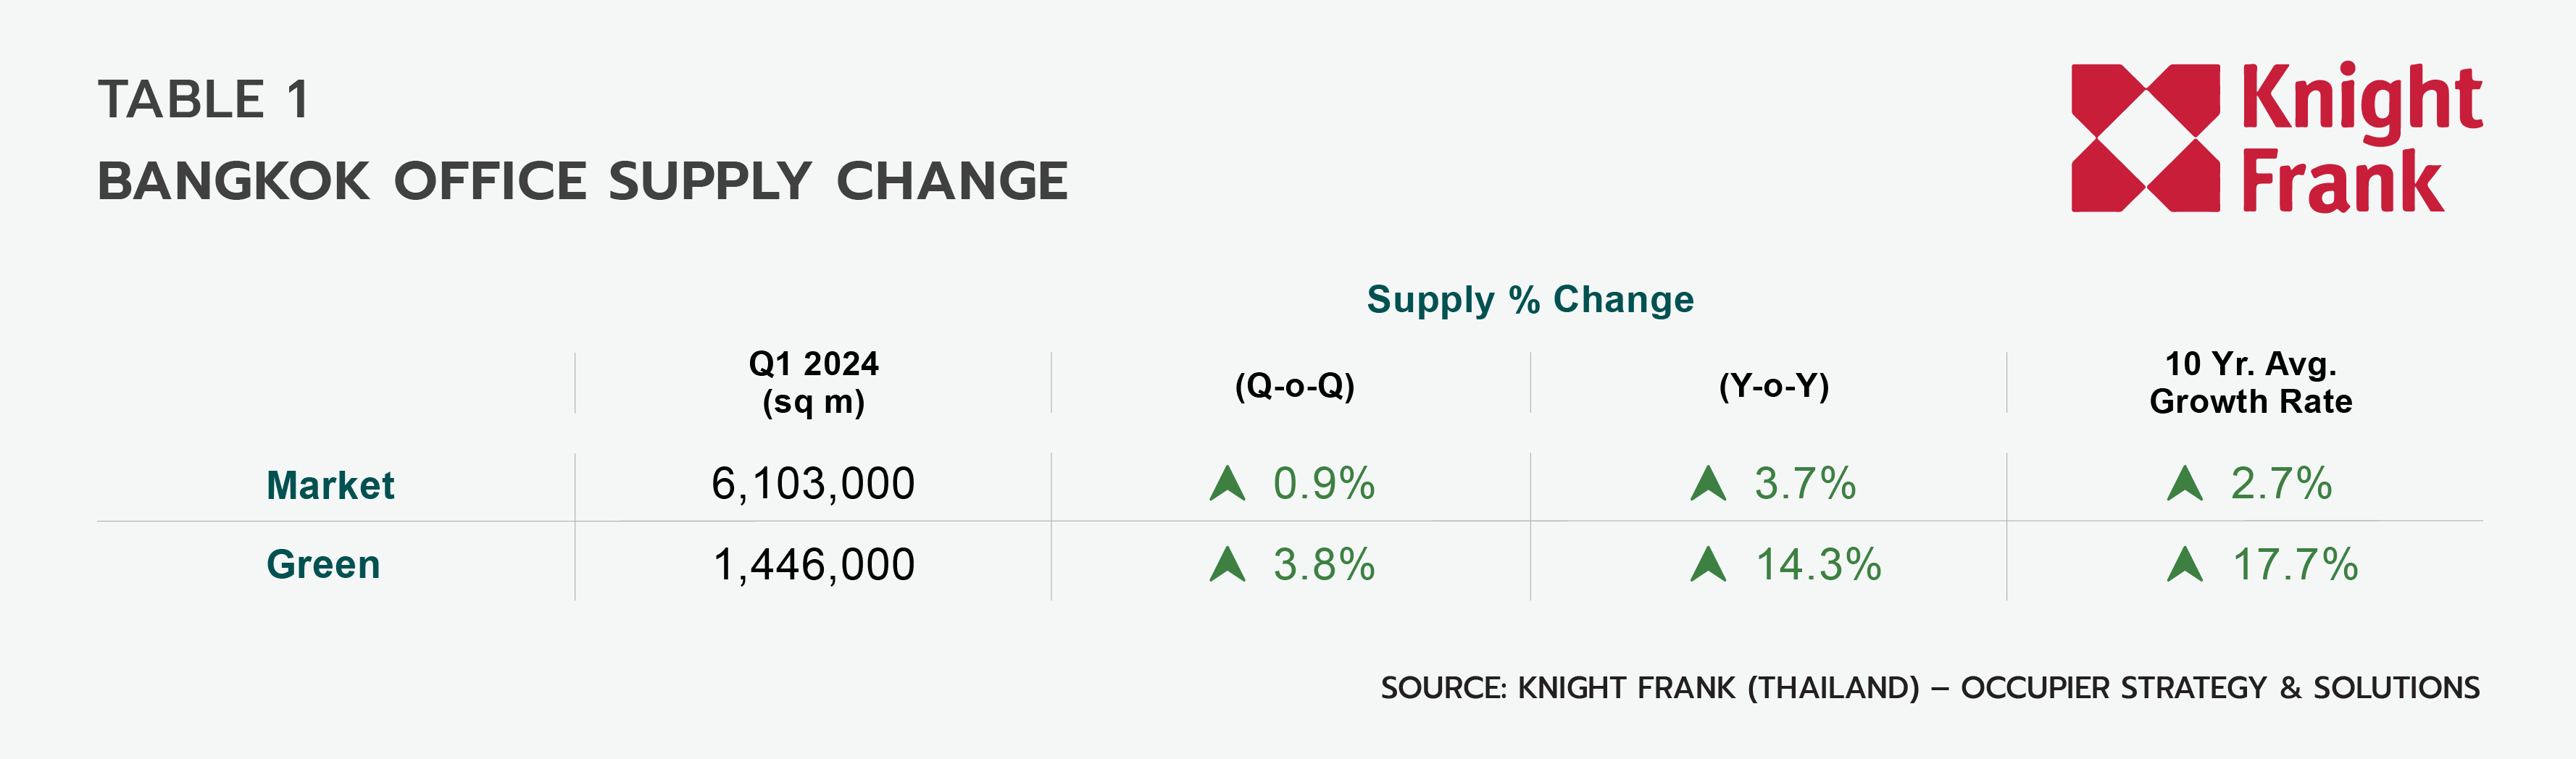
Bangkok's total supply of office space expanded this quarter by 52,700 sq m, or by 0.9% QoQ, to 6.10 million sq m. Two new buildings were launched in Q1, including the Punn Tower on Rama 4 Road and JLK Tower, connected to BTS Nana. Since all new supply is classified as green buildings, the lettable area of green office space also increased by 3.8% QoQ to 1,446,000 sq m, now accounting for 24% of the total market.
Read more the full research here