
Bangkok Office Market Q4 2023
The office environments are undergoing a transformation in the post-pandemic era, with denser workspace being counterbalanced by a commitment to high-quality, wellness-centric design.
05 March 2024
Economic Overview
Thailand's economic growth continued its slow recovery in Q4, with an expected growth rate of 2.4% in 2023, according to the Bank of Thailand. Private consumption remained the economic engine, driven by the service sector and improvements in labor income. However, tourism started to slow down due to lower than expected arrivals from China. Fixed capital investment also experienced moderate growth, while government expenditure contracted considerably as COVID-19 relief measures and stimulus packages were phased out. Moreover, the delay in the approval of the FY2024 budget expenditure Act is likely to decrease government investment until Q1 2024. On the external front, Thailand maintained a positive trade balance, due to an increase in exports of goods and services that surpassed a decline in imports.
On the financial stability front, the average headline inflation for 2023 is forecast to be 1.3%, which falls within the Bank of Thailand's target range of 2%. This lower inflation rate is attributed to the high base effect from last year, along with the government's temporary energy subsidy. However, there is a risk of rising food prices due to El Niño and global supply chain disruptions, which could be exacerbated by the ongoing conflict in the Middle East and the Russia-Ukraine war, potentially exerting upward pressure on price levels in 2024. Meanwhile, following the policy rate hike, interest rates paid on loans have been observed to surpass those received from deposits. This trend is evident in the banking sector's increased net interest margin (NIM), which has risen from 2.6% in 2022 to 3.1% in 2023. Consequently, the tightening credit conditions are likely to impose constraints on new investments and corporate expansion.
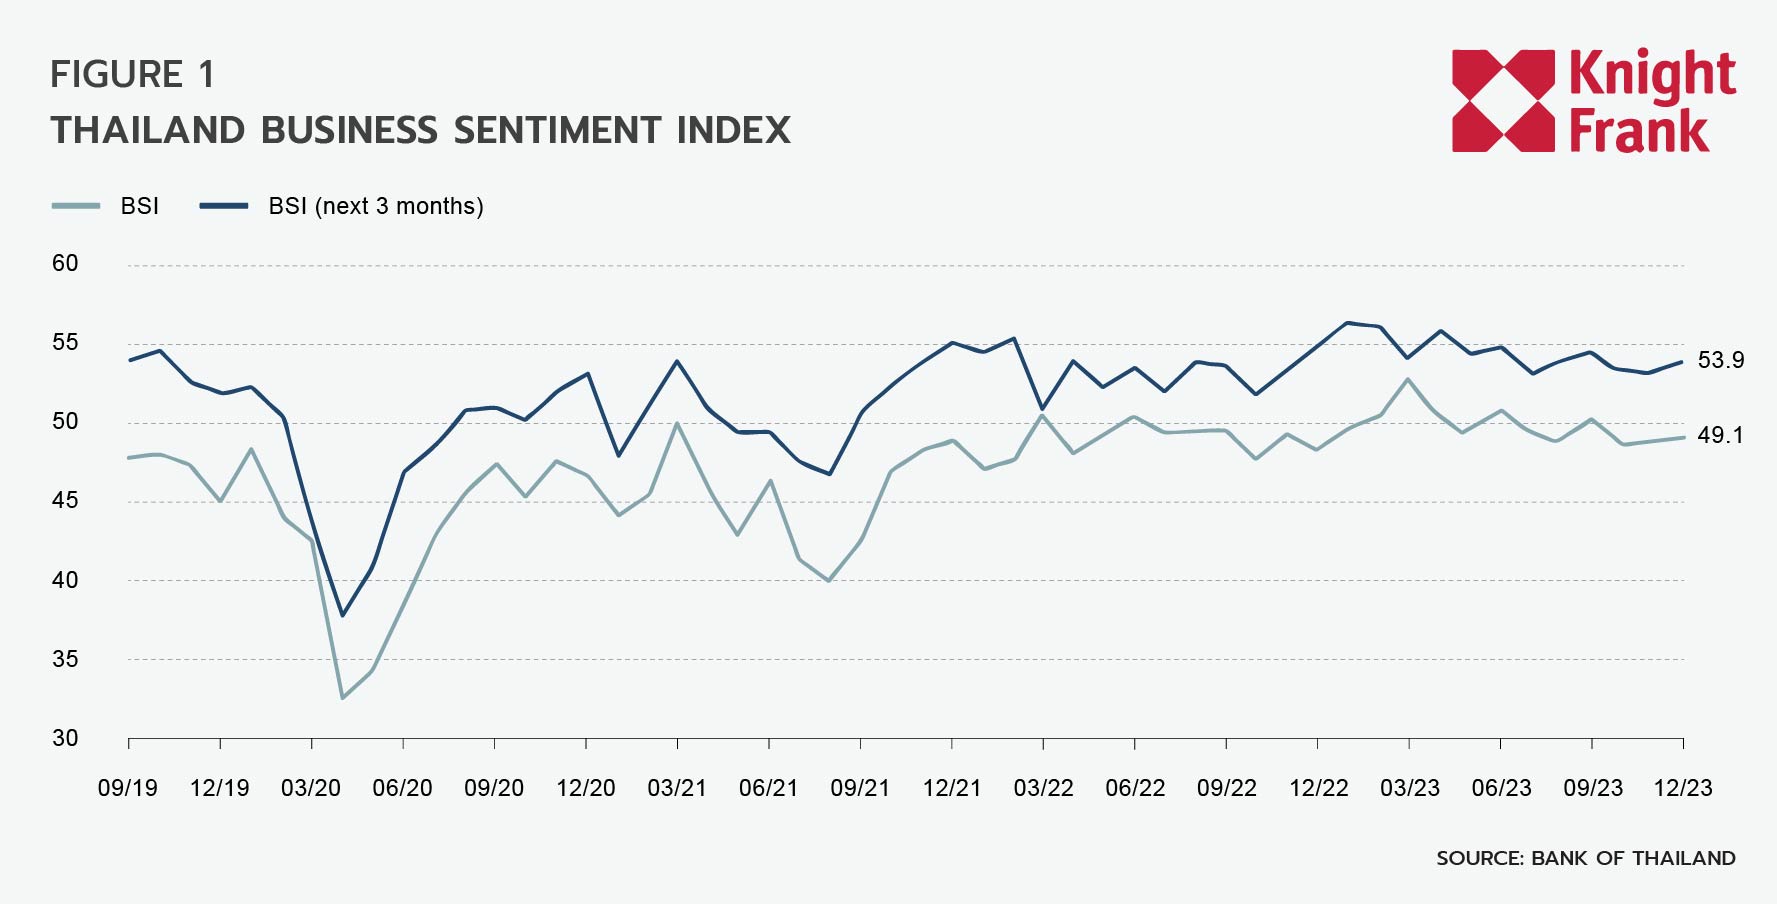
The Business Sentiment Index (BSI) for December 2023 remained stable at 49.1, unchanged from the previous quarter. Confidence in total order books and production increased, while the employment and investment sub-indices declined. Meanwhile, the projected BSI for the next three months increased by 1.3 points to 53.9 across almost all components, particularly production and overall firm performance.
Read the full report here